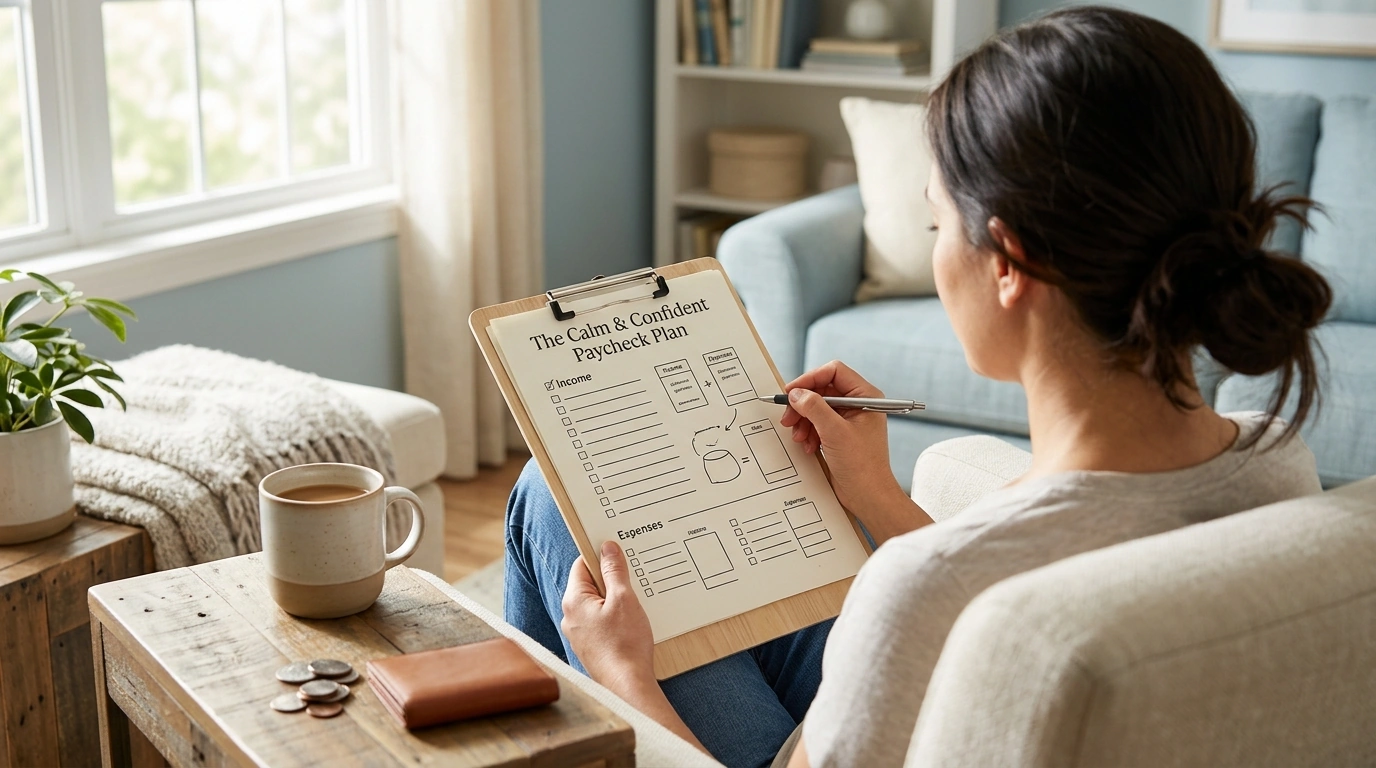
A paycheck can feel like it disappears the moment it lands. A calmer approach is to give every dollar a job, automate what matters, and review on a predictable rhythm. The plan below breaks salary management into small actions that build control fast—without complicated spreadsheets.
Before you set any “rules,” lock down what’s actually available to spend and save. Clarity here prevents the most common budgeting mistake: planning with money you never receive.
| Item | Amount | Notes |
|---|---|---|
| Gross pay | $ | Before taxes and deductions |
| Taxes withheld | $ | Federal/state/local, FICA |
| Pre-tax benefits | $ | 401(k), HSA, insurance |
| Net pay (take-home) | $ | Amount that hits checking |
| Automatic transfers | $ | Planned moves to savings/investing |
If your net pay surprises you, update your withholding settings using the IRS Tax Withholding Estimator so your paycheck plan is built on real numbers.
Essentials are the foundation of a paycheck system. When they’re covered first, the rest of the plan becomes far less stressful.
| Bill | Due date | Total | Monthly set-aside |
|---|---|---|---|
| Car insurance | Every 6 months | $600 | $100 |
| Annual membership | 1x per year | $120 | $10 |
| Holiday spending | Dec | $500 | $42 |
If you need a quick refresher on structuring a basic budget, the CFPB budgeting resources offer simple, trustworthy guidance you can adapt to your pay cycle.
The best system is the one you’ll repeat. Pick one structure and run it for a full month before tweaking.
| Category | Target per paycheck | How it’s handled |
|---|---|---|
| Fixed bills | $ | Autopay from bills account |
| Essentials (groceries/gas) | $ | Weekly transfer to spending |
| Savings goals | $ | Automatic transfer day after payday |
| Debt payoff | $ | Extra payment scheduled |
| Fun money | $ | Small, guilt-free cap |
Automation turns “good intentions” into defaults. Once the basics run on rails, the only remaining job is to supervise.
Layered savings prevents a single unexpected expense from knocking you off course. Each layer has a different job.
For a simple, consumer-friendly overview of building a workable spending plan, the Federal Trade Commission guide to making a budget is another helpful reference.
A practical target is 5%–20% of take-home pay, starting smaller if cash is tight and increasing as fixed costs stabilize. The 50/30/20 framework is a useful reference, but your best rate is the one that funds your emergency layer and goals without triggering overdrafts. For example, with a $2,000 biweekly net paycheck, saving 10% means transferring $200 the day after payday.
Fund upcoming bills first, then send a fixed weekly transfer to your spending account for groceries, gas, and extras. Using a dedicated “bills” account keeps autopay clean and prevents accidental spending. Also plan ahead for the two months each year that include three paychecks, and decide in advance whether that “extra” check goes to debt, savings, or sinking funds.
Set caps for a few high-impact categories (like eating out, groceries, and online shopping) and check them once a week instead of logging every item. Many people find it easier to use a separate account or a dedicated card for discretionary spending so the limit is built in. Alerts for low balances and large transactions add guardrails without constant tracking.

Leave a comment